- Digital Political Economy
Financial Sovereignty: How QRIS Broke the Global Credit Card Monopoly
In the world of finance, there have been a handful of payment networks that have dominated for decades, and the West is their home. The giants of the industry, Visa and Mastercard, have been the main regulators of digital commerce for years, allowing trillions of dollars in transactions to take place globally.

Tazegul Nyyazmammedova
In the world of finance, there have been a handful of payment networks that have dominated for decades, and the West is their home. The giants of the industry, Visa and Mastercard, have been the main regulators of digital commerce for years, allowing trillions of dollars in transactions to take place globally. This duopoly not only offered the standardisation of infrastructure but also significant costs to developing economies such as high cost of transactions, dependence on foreign controlled systems etc. But there is a secret revolution taking place in Southeast Asia, spearheaded by the Quick Response Code Indonesian Standard (QRIS). QRIS has not only defied the global monopoly of credit card payments in Indonesia but has also become a beacon of financial sovereignty. This essay examines the role of QRIS in driving national economic resiliency, financial inclusion, and a growing global movement toward a decentralized financial system.
Before understanding the importance of QRIS, it is important to understand the magnitude of the global credit card monopoly. For much of the latter 20th Century, any business that took electronic payments was forced to either connect to Visa or Mastercard. These networks offered trust and infrastructure for a certain "tax" for each transaction. These charges in developing countries such as Indonesia typically covered 2% to 4% of small business profits. Moreover, these networks created a country's digital economy to be dependent on other companies. This resulted in a strategic weak point as if a country could be sanctioned by the other countries or if these private entities change their conditions, the national payment system could be paralysed. Financial sovereignty, which means that a country can have control over its own payment rails and that its economic lifeblood is within its own jurisdiction, is the power of a nation to do so.(Permatasari et al., 2026)
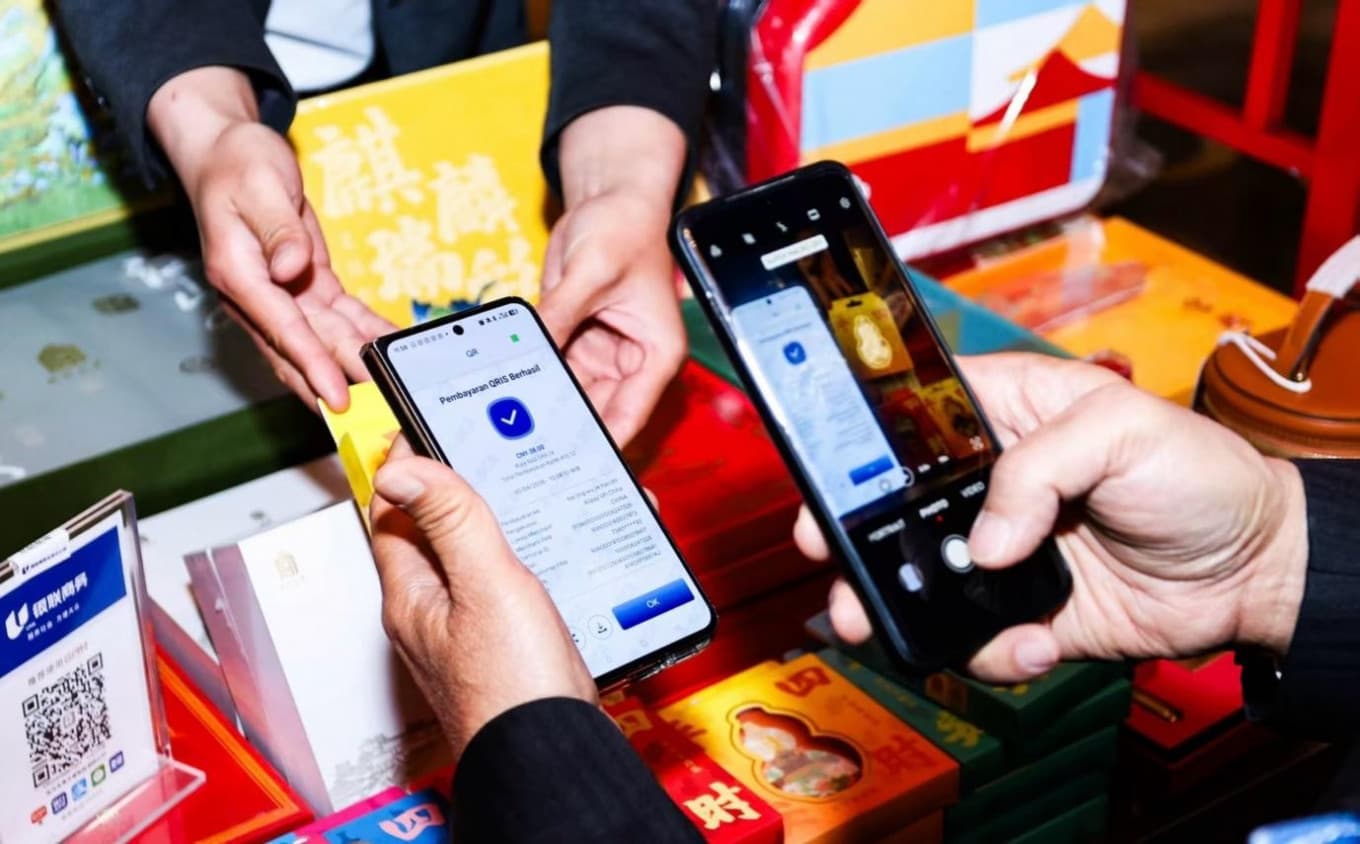
To fulfill this need of sovereignty and efficiency, Bank Indonesia launched QRIS in 2019. Prior to the launch, the digital payment market in Indonesia was disjointed, having each different e-wallet service provider employing its own non-interoperable QR code. A merchant frequently would be required to show several codes to please various customers. QRIS addressed this by developing a standard that could be used by all e-wallets or mobile banking apps to scan and pay at any merchant. The technical interoperability was complemented by the Gerbang Pembayaran Nasional (GPN), which would allow domestic transactions to be made inside Indonesia, instead of being switched through international switching centers in the western countries. Indonesia's decision to maintain local data and processing costs would effectively restore the government over its digital financial infrastructure.
This change has had a dramatic effect. QRIS quickly took the place of the traditional card networks in terms of market share within a few years of its launch. According to reports, Visa's market share, which was 57%, has declined to about 38% due to the shift of consumers and merchants to QRIS, which is cheaper. The impact is most felt on micro, small, and medium enterprises (MSMEs). Having a credit card terminal was difficult and expensive for a street vendor or a small village shop. QRIS, however, only needs a QR code that has been printed. This has enabled millions of people who were not banked before to join the formal economy. QRIS has created a financial inclusion that would not be possible with traditional financial networks that are cumbersome and expensive to operate.
This step towards financial sovereignty, however, has not gone unnoticed. Recently, the United States government and international trade groups have voiced concerns about QRIS and other national standards, calling them "trade barriers. The argument is that the preference for domestic systems and the technical requirements that are difficult for foreign players to comply with, make free trade more difficult in Indonesia. These criticisms are seen by people in Jakarta as an effort to preserve a 'legacy monopoly' that is no longer beneficial for developing countries. The tension is a reflection of the basic quarrel between the new digital age of national autonomy and the well-established world of globalized finance. Indonesia's counter-action is not just a trade issue; it's a matter of the right to create a robust and autonomous economic base free from external influences.(Mutaqin & Singarimbun, 2025)
The success of QRIS is an example of a larger worldwide effort. The Unified Payments Interface (UPI) has accomplished similar feats in India, handling billions of transactions and putting card networks on the back burner. The Pix system has changed the way money is transferred in Brazil. These systems are becoming more interconnected, coast to coast, bypassing the traditional global banking system that is based on dollars. Indonesia has already started cross-border QRIS initiatives with other ASEAN neighbouring countries, such as Thailand, Malaysia and Singapore. This will enable a traveller from Jakarta to pay for the meal in Bangkok with his/her Indonesian wallet but the transaction will be processed directly between the central banks. The regional integration is a key development in the evolution of a multipolar financial world, within which regional financial blocks may trade without the intervention of a global financial block. (Qris: Indonesia’s Most Successful and Most Dangerous Digital Project? | by Favian Rafif | The Political Prism | Medium, n.d.)
To sum it up, QRIS is a significant step toward achieving financial sovereignty. Indonesia is breaking the monopoly of credit cards in the world, which proves that a developing country can create a world-class digital payment system that has a primary focus on the citizens of that country. The system has demonstrated that efficiency and inclusion do not have to be compromised at the very cost of national independence. The overseas countries have not been happy about the change, but the savings and control over the internal market are too great to overlook. While a monopoly of global credit cards may be fading in the wake of Indonesia, India, and Brazil, the future of finance in the world is becoming more diverse, resilient, and sovereign. The QR code is now the key which broke the links of financial dependency.
References
- Mutaqin, F., & Singarimbun, L. (2025). US labels QRIS a trade barrier – what’s next for Indonesia’s digital payment system? https://doi.org/10.64628/AAN.XPTY9D7J7
- Permatasari, N. Y., Dwiguna, E., Rahayu, S. A., Tamba, C. Y. M., Silalahi, R. G., & Buana Muslim, B. L. B. (2026). Transformasi Sistem Pembayaran Internasional: QRIS Mengguncang Dominasi Visa dan Mastercard. IJMA (Indonesian Journal of Management and Accounting), 7(1), 46–56. https://doi.org/10.21927/IJMA.2026.7(1).46-56
- Qris: Indonesia’s Most Successful and Most Dangerous Digital Project? | by Favian Rafif | The Political Prism | Medium. (n.d.). Retrieved August 6, 2026, from https://medium.com/the-political-prism/qris-indonesias-most-successful-and-most-dangerous-digital-project-21fd059c4752
- Digital Political Economy